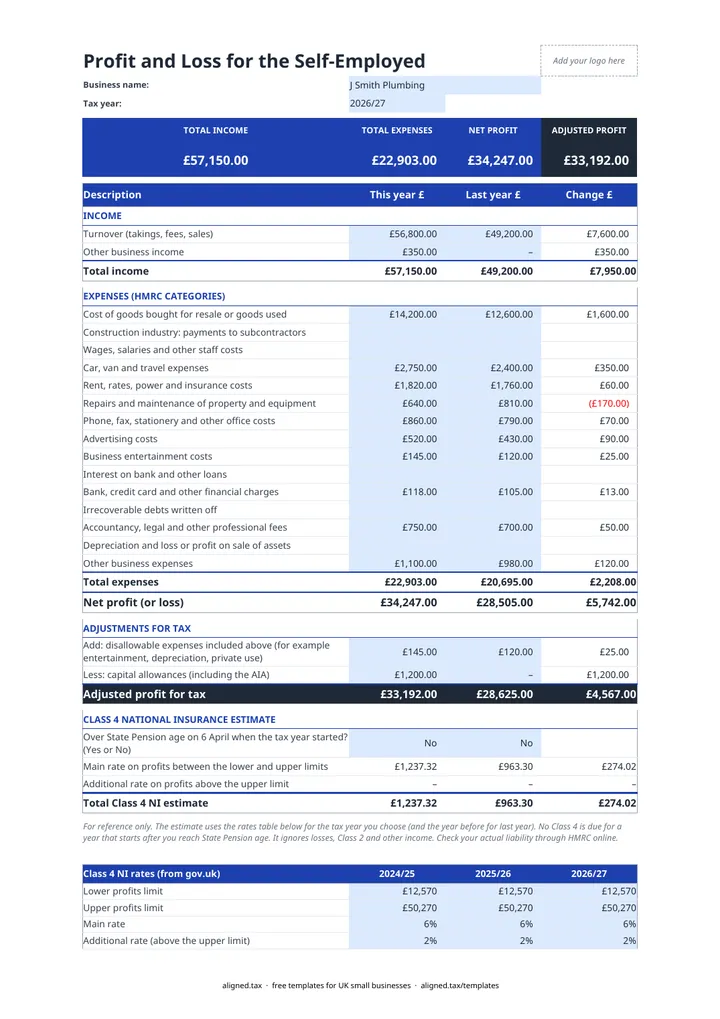
This free profit and loss template is built for UK sole traders. It sets out a year’s income and expenses in HMRC’s own self-employment categories, so the totals match your tax return and your MTD quarterly updates. It then adds back disallowable costs, takes off capital allowances and estimates Class 4 National Insurance on the adjusted profit.
What is on the sheet?
The P&L Self-Employed sheet runs from top to bottom in four blocks:
- Income: Turnover (takings, fees, sales) and Other business income.
- Expenses (HMRC categories): all 15 headings from the self-employment pages of the tax return, including construction industry payments to subcontractors, business entertainment, irrecoverable debts written off, and depreciation.
- Adjustments for tax: disallowable expenses added back and capital allowances (including the Annual Investment Allowance) deducted, giving Adjusted profit for tax.
- Class 4 National Insurance estimate: the main rate and the additional rate, worked out from a rates table for the tax year you pick.
There are three columns: This year £, Last year £ and Change £, so you can see at a glance which costs moved.
Why record costs that are not allowable?
Your accounts should show what the business really spent. Entertainment, depreciation and the private share of a phone or car are genuine costs, but HMRC does not allow them against tax. Keeping them in the expense rows and adding them back in one place makes the adjustment clear to you, your accountant and HMRC.
Class 4 rates in the template
| Tax year | Main rate | Profits band | Additional rate |
|---|---|---|---|
| 2024/25 to 2026/27 | 6% | £12,570 to £50,270 | 2% above £50,270 |
No Class 4 is due for a tax year that starts after you reach State Pension age, so the sheet has a Yes or No for each year. The estimate ignores losses, Class 2 and other income, so treat it as a guide.
From profit and loss to Making Tax Digital
If your qualifying income is over £50,000, MTD for Income Tax applies from April 2026. The threshold falls to £30,000 from April 2027 and is due to fall to £20,000 from April 2028. The MTD guide for sole traders explains what changes. Because this template already uses HMRC’s categories, moving your figures into quarterly updates needs no recoding. To upload records to aligned.tax, save them as an .xlsx file.